Renewing soon? See what 50+ lenders would offer before you sign your renewal. Compare my renewal

Mortgage News · Nov 8, 2026 · 1 min read

Debt consolidation math: when rolling debt into your mortgage makes sense

Consolidating can free up serious cash flow — but it isn’t free. Here’s how to weigh monthly savings against long-term cost.

Debt consolidation math: Balo Financial guide to rolling credit card debt into your mortgage

When credit cards charge 20% or more and car loans and lines of credit add up, a debt consolidation refinance can replace several payments with one mortgage payment at a much lower rate.
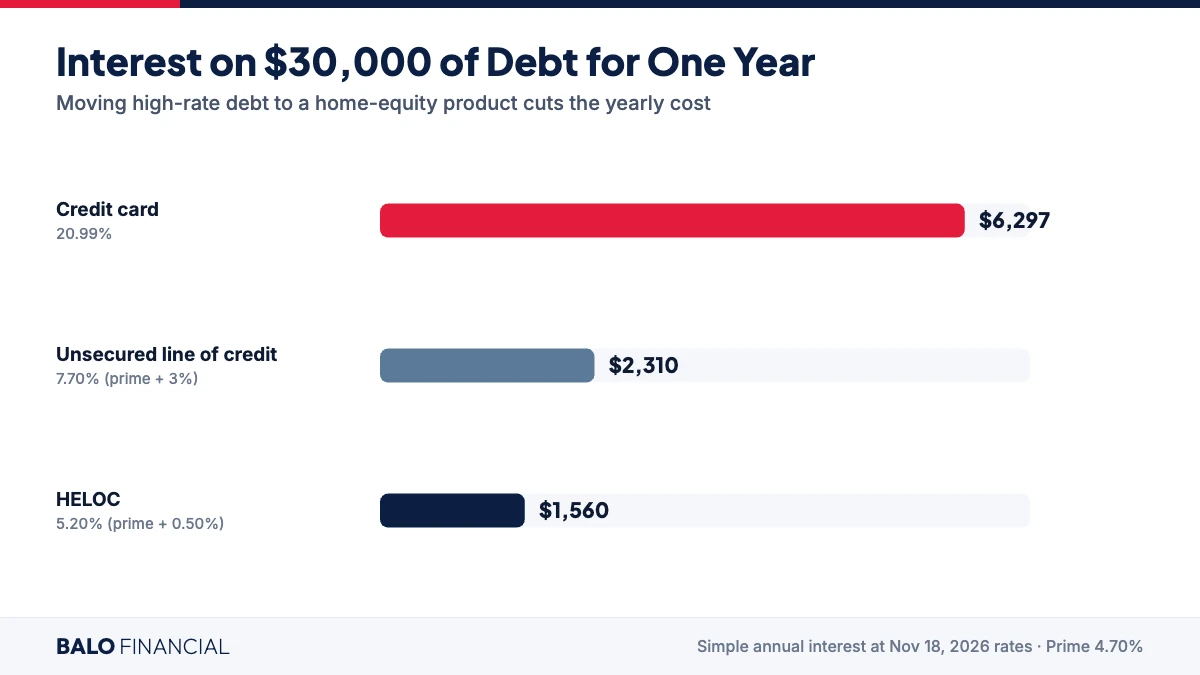
Chart of one year of interest on $30,000: credit card $6,297, unsecured line of credit $2,310, HELOC $1,560
One year of simple interest on $30,000 at November 2026 rates.

The upside

  • Lower total monthly payments — often by hundreds of dollars.
  • One payment instead of many.
  • Lower credit utilization, which may help your score recover.

The trade-offs

  • Short-term debt is spread over a long amortization, which can increase total interest if you don’t pay it down faster.
  • Breaking your current mortgage early can trigger a penalty.
  • Legal and appraisal costs may apply.

Make it a plan, not a reset

The best consolidations redirect part of the monthly savings into extra mortgage payments, so the consolidated debt disappears years sooner. We’ll show you the full picture — monthly savings, penalty, total interest — before you decide.
Will BaloMortgage Agent · Balo Financial
Keep reading

More insights

Ready when you are

Your next step takes two minutes.

Start online now, or talk it through with a licensed agent. Either way, you’ll know your options today.

  • No credit check to start
  • No obligation
  • No cost on most mortgages
Call Get pre-approved