Congratulations on your new mortgage. Your financing has been placed with Neo Mortgage, the home-lending arm of Neo Financial. This guide explains who Neo is, the benefits that come with your mortgage, and how to get help with your account after closing.
Keep it handy. Most of the questions homeowners have in the first few years, from making extra payments to changing banks, are answered below.
TL;DR
Your mortgage is with Neo Mortgage, a licensed lender from Calgary-based fintech Neo Financial. You get a competitive rate, no hidden fees, and prepayment privileges of up to 20% a year. Neo says the mortgages it services are government-guaranteed, so your terms are protected until renewal. For account servicing, contact Neo using the number that matches your mortgage number. For advice, renewals or any big change, contact your mortgage broker first.
In this guide
Who is Neo Financial?
Neo Financial is a Canadian financial technology company headquartered in Calgary. It was founded in 2019 by the team that built SkipTheDishes, led by co-founder and CEO Andrew Chau. Neo runs without branches and offers credit cards, savings, investing and mortgages to Canadians.
Neo officially launched Neo Mortgage in May 2023. Its goal is to make mortgages more affordable, efficient and accessible through technology, while keeping licensed Mortgage Advisors available to borrowers.
Neo Mortgage Services Inc. is licensed across most of Canada, including Ontario (FSRA #13444), British Columbia, Alberta, Saskatchewan, Manitoba and Atlantic Canada. Neo partners with established financial institutions to deliver its products.
Your mortgage at a glance
Your mortgage commitment and closing documents list your exact terms. Here’s what each part means.
What makes up your payment
- Principal: the part that pays down the amount you borrowed.
- Interest: the cost of borrowing, calculated on your remaining balance. Early in your mortgage, most of each payment is interest; over time, more goes to principal.
- Property taxes: owed to your municipality. Depending on your setup, you pay them directly or through your mortgage payment.
- Home insurance: required by your lender to protect the property.
Your rate type
| Rate type | How it works | What it means for you |
|---|---|---|
| Fixed | Your rate stays the same for the whole term | Predictable payments, no matter what rates do |
| Adjustable | Your rate moves with the Bank of Canada’s prime rate | Your payment can go up or down during the term |
Your mortgage type
- Insured: you put down less than 20%. A default-insurance premium was added to your loan amount. Insured mortgages often get some of the lowest rates available.
- Conventional: you put down at least 20% and didn’t need default insurance.
- Uninsured: used for homes over the insured price limit, refinances that take equity out, or other files that don’t qualify for insurance.
Key dates to know
- Interest adjustment date: the date your regular payment schedule officially starts. Your prepayment privileges also start here.
- Anniversary date: each year from the interest adjustment date. Your prepayment room resets on this date.
- Maturity date: the end of your term. This is when you renew or switch lenders without a penalty.
The benefits of your Neo mortgage
1. A competitive rate
Neo built its mortgage business on rates that beat the Big 5 banks’ posted rates. Your rate was chosen to fit your situation.
2. No hidden fees
Neo promises “no surprises, no hidden fees.” Any servicing fees are listed openly in Neo’s mortgage fee schedule.
3. Room to pay it off faster
Your mortgage includes prepayment privileges (details from Neo):
- Increase your regular payment by up to 20% of your original payment.
- Make lump-sum payments of $100 or more once a year, up to 20% of your original principal.
- These start from your interest adjustment date and reset each anniversary.
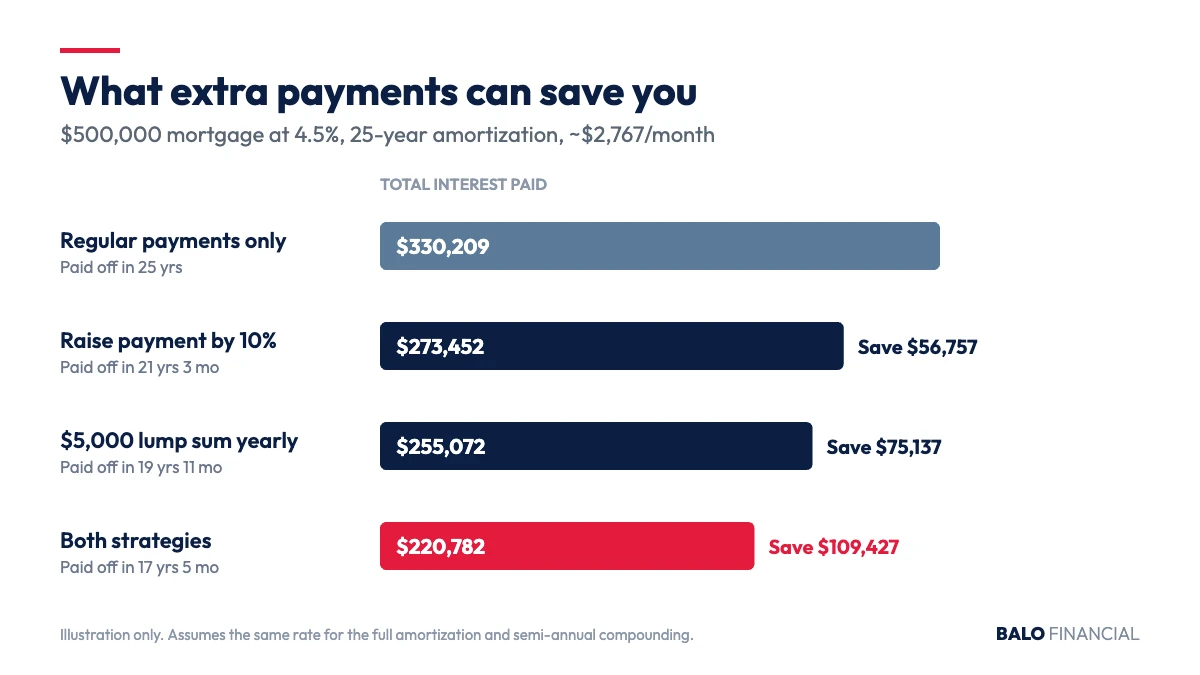
Using them, even modestly, can save you a lot. Here’s an example: a $500,000 mortgage at 4.5% with a 25-year amortization and a monthly payment of about $2,767.
| Strategy | Mortgage paid off in | Total interest | Interest saved |
|---|---|---|---|
| Regular payments only | 25 years | $330,209 | — |
| Raise payment by 10% (about $277/month) | 21 years, 3 months | $273,452 | $56,757 |
| $5,000 lump sum once a year | 19 years, 11 months | $255,072 | $75,137 |
| Both of the above | 17 years, 5 months | $220,782 | $109,427 |
For illustration only. Assumes the same rate for the full amortization, monthly payments and semi-annual compounding. Your results will depend on your rate, balance and renewal terms.
4. Your mortgage is protected
Neo says the mortgages it services are government-guaranteed and managed by Computershare Trust. If anything ever happened to Neo, your mortgage terms would stay exactly the same until renewal.
5. Licensed advisors, not salespeople
Neo’s Mortgage Advisors are licensed professionals, and Neo describes them as commission-free.
6. A modern, digital lender
Neo is built for online service, so renewing or switching later can be handled digitally, without branch visits.
How to manage your mortgage after closing
Who you contact depends on your mortgage number, which is on your mortgage documents and statements. Per Neo’s help centre:
| Your mortgage number | Phone | Hours | |
|---|---|---|---|
| Starts with “N” | 1-866-290-2649 | requests@servicing.neofinancial.com | Mon–Fri, 6:30 a.m.–5 p.m. MT |
| Any other format | 1-833-591-3201 | neomortgage@lenderservices.ca | Mon–Fri, 8 a.m.–8 p.m. |
Good to know
- Your mortgage isn’t in the Neo app. Changes are made by phone or email with the servicing team above.
- Changing the bank account your payments come from: email a written request plus a void cheque or bank-stamped pre-authorized debit form at least 3 business days before your next payment.
- Other changes (property address, names on the mortgage, prepayments): email the details with supporting documents, and the servicing team will guide you.
Important terms to keep in mind
- Use your prepayments each year. Unused prepayment room does not carry over to the next year.
- Stay within your limits. Paying more than your annual privileges allow counts as breaking the mortgage and can trigger a penalty.
- Breaking your term early has a cost. On a closed fixed rate, the penalty is the greater of three months’ interest or the interest rate differential (IRD). On a closed adjustable rate, it’s three months’ interest. Refinancing, renewing early or moving to another lender mid-term can all trigger it.
- Adjustable-rate payments can change. If you chose an adjustable rate, your payment moves with the Bank of Canada’s prime rate.
- Talk to your broker before any big change. Before you sell, refinance, switch or renew, a quick call can save you from an avoidable penalty and make sure you get the best option at the time.
How the interest rate differential (IRD) works
The IRD makes up for the interest your lender loses when you break a fixed term early. It’s based on the difference between your rate and the rate the lender could charge today for the time left on your term, multiplied by your balance.
When rates have dropped since you signed, the IRD can be much larger than three months’ interest. When rates have risen, three months’ interest is usually the larger amount. Ask the servicing team for an exact penalty quote before you make any decision.
Your renewal: what to expect
Your term ends on your maturity date, which comes well before your mortgage is fully paid off. At that point you can renew with Neo or move to another lender, without a penalty.
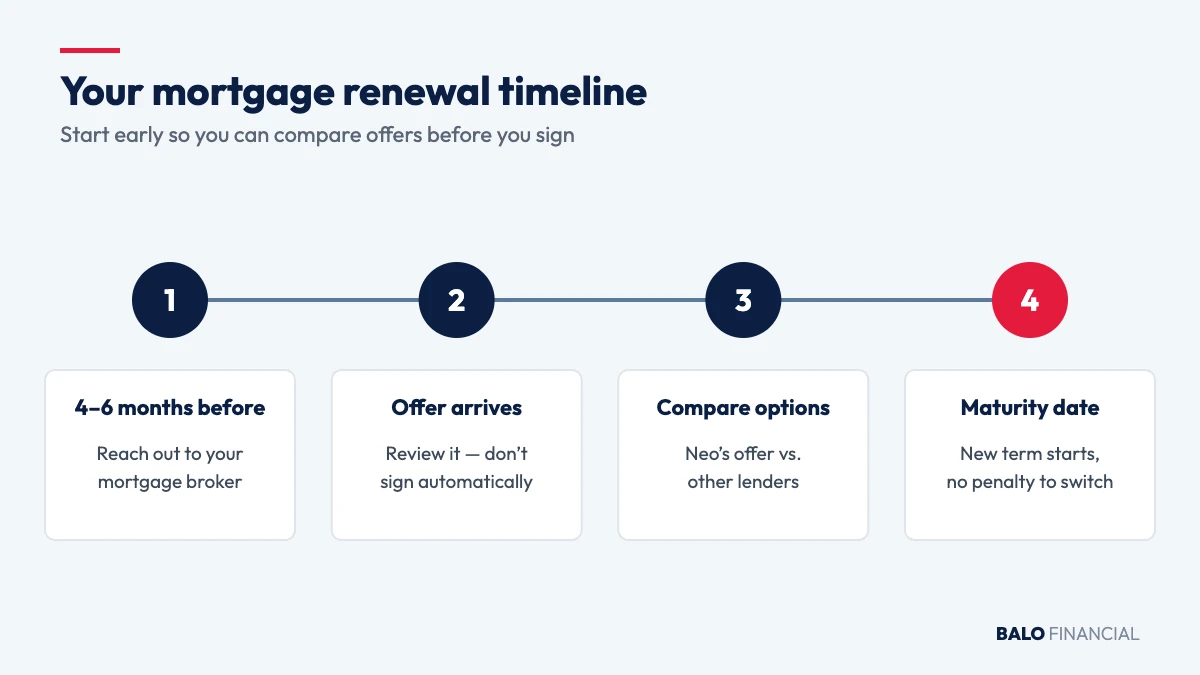
- About 4 to 6 months before maturity: reach out to your mortgage broker. Many lenders let you hold a rate for 120 days or more, so this is the right time to start comparing.
- When your renewal offer arrives: don’t sign it automatically. The first offer isn’t always the best rate available.
- Compare your options: your broker can check Neo’s offer against other lenders and look at whether a different term, rate type or amortization fits your plans better.
- Lock in and sign: once you’ve chosen, your new term starts on the maturity date with no gap in payments.
Renewal is also a good time to review your goals: paying the mortgage off faster, freeing up cash flow, or using your equity for renovations or debt consolidation.
Frequently asked questions
Is Neo a bank? Is my mortgage safe?
Neo is a fintech company that works with established financial institutions. Neo says the mortgages it services are government-guaranteed and administered by Computershare Trust, so your terms are protected until renewal even if something happened to Neo.
Where do I send my payments?
Payments come out automatically from the bank account you set up at closing. To change accounts, contact the servicing team shown in the table above.
Can I see my mortgage in the Neo app?
Not currently. Neo manages mortgages by phone and email through its servicing team.
How do I make an extra payment?
Contact the servicing team for your mortgage number. You can prepay up to 20% of your original principal each year, in lump sums of $100 or more.
What happens when my term is up?
You’ll need to renew, either with Neo or by switching to another lender. Reach out to your mortgage broker a few months ahead so your options can be compared before you sign.
Who do I call with a question?
For account servicing, use Neo’s contacts above. For advice on your mortgage or your next move, contact your mortgage broker.
What if I need to sell my home before my term ends?
Call your mortgage broker before you list. Breaking the mortgage can trigger a penalty, and the right plan depends on your terms, your timing and whether you’re buying again.
What if I can’t make a payment?
Contact Neo’s servicing team right away, before the payment is missed. Lenders have more options when you reach out early, and a missed payment can affect your credit.
Can I change my payment amount or frequency?
You can raise your regular payment within your prepayment privileges. For other changes, such as payment frequency, contact the servicing team to see what your mortgage allows.
Can I take equity out of my home later?
Possibly, through a refinance. Refinancing before your maturity date can trigger a penalty, so talk to your broker first about timing and alternatives. For smaller needs, see our guide to HELOCs vs. personal loans vs. lines of credit.
Questions? I’m here to help
Neo handles the day-to-day servicing of your mortgage. I’m still your mortgage broker for the life of your mortgage, and you can reach out anytime, including:
- Before you sell, refinance or make any big change
- When renewal is coming up, about 4 to 6 months before your maturity date
- If you want to pay your mortgage off faster or free up cash flow
- If you’re thinking about a rental, a cottage or your next home
- If friends or family need mortgage advice
Will Balo — Balo Financial
Email: will@balofinancial.com
Website: balofinancial.com
Referrals are the best compliment I can receive. If you know someone buying, renewing or refinancing, I’d be glad to help them too.
The bottom line
Your mortgage is with a modern, licensed Canadian lender that offers competitive rates, transparent fees, strong prepayment privileges and protection for your mortgage terms. Save Neo’s servicing contacts, use your prepayment room when you can, and check in with your mortgage broker before renewal or any major change.
Sources
- Neo Mortgage – Neo Financial
- Manage your mortgage from Neo – Neo Financial Help Centre
- Guide to getting a mortgage from Neo – Neo Financial Help Centre
- About Neo Financial
- Neo Financial Launches Neo Mortgage – Business Wire, May 2023
This article is for general information only and isn’t financial advice. Your mortgage commitment and documents set out your exact terms; contact details and policies are set by Neo Financial and may change.